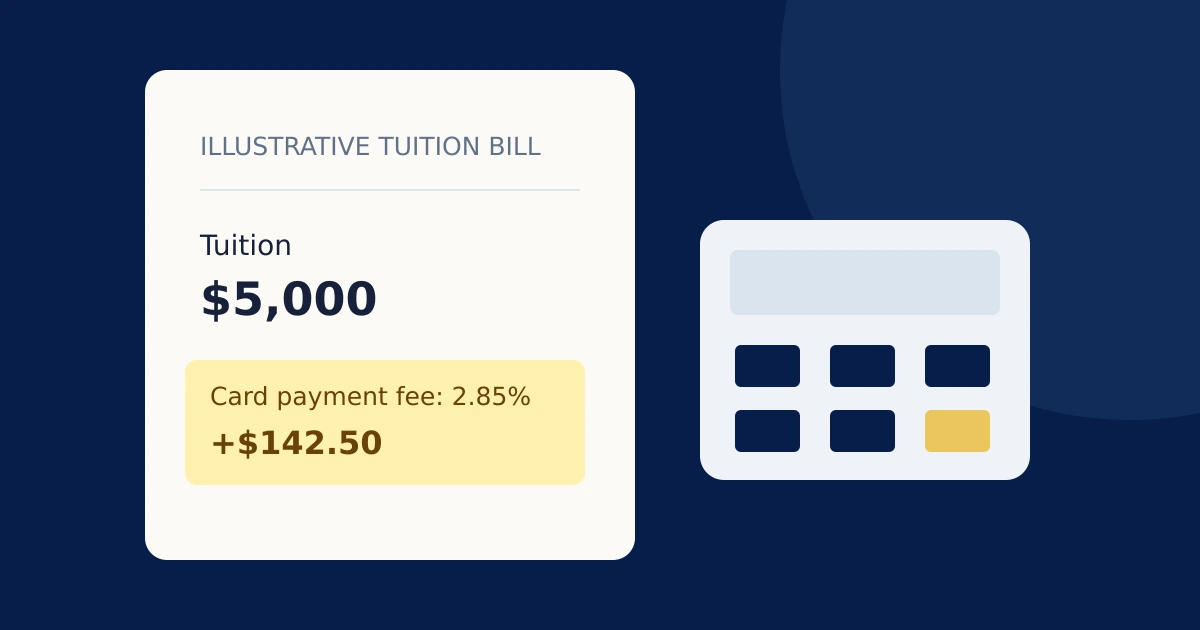
Should you pay college tuition with a credit card to finish a welcome bonus? One bill could complete the spending requirement, but the school’s processing fee may cost more than your rewards. Open the payment screen and compare the full checkout amount before charging it.
The school’s payment rules come first
There is no universal tuition credit-card fee. UC San Diego, for example, lists a 2.85% nonrefundable service fee for domestic card payments and 3.25% for international cards through its processor. Those are that school’s published terms, not a rate to assume at another institution. UC San Diego also lists a $0.50 e-check fee, so its bank-payment alternative is lower-cost rather than free.[1]
Check whether the school accepts your card, which charges can be paid by card, whether the fee appears as a separate transaction, and what happens to that fee after a refund. A refunded class charge does not necessarily undo the processing cost.
Also look for a bank-transfer option and an installment plan. Wofford, for example, lists a no-additional-fee ACH option and a semester payment plan with an enrollment fee. Availability, deadlines, and plan costs are school-specific.[2]
A $5,000 bill: the fee can exceed the rewards
Assume a hypothetical $5,000 tuition payment, a 2.85% fee, and a card earning 2% on the tuition purchase. For this first calculation, assume the processing fee earns no rewards and the statement is paid in full.
- Tuition
$5,000.00 - Processing fee
$5,000 × 2.85% = $142.50 - Purchase rewards
$5,000 × 2% = $100.00 - Extra cost versus a no-fee bank payment
$142.50 − $100.00 = $42.50
If the entire $5,142.50 charge earns 2%, rewards rise to $102.85 and the net cost falls to $39.65. It is still more expensive than a no-fee bank payment. Against a $0.50 e-check instead, the extra card costs would be $42.00 or $39.15, respectively. Confirm how the fee is charged and treated rather than silently counting rewards on it.
When a welcome bonus could change the answer
Keep ordinary rewards and the incremental bonus separate. Suppose the same eligible purchase is the final spending needed for a hypothetical $200 cash bonus, and you would otherwise miss it. With no rewards on the processing fee, the math becomes $100 + $200 − $142.50 = $157.50 ahead, before interest or other costs.
Read the actual offer for eligible purchases, the deadline, prior-bonus restrictions, and the effect of refunds. Check whether your issuer counts the transaction date, posting date, or another date under that specific offer; a payment initiated before the deadline may post later. Do not rely on tuition being refundable as a way to manufacture qualifying spending.
Use our welcome-offer spending guide to plan the remaining requirement with purchases already in your budget.
Rewards math is incomplete if you will carry the balance
A purchase grace period can avoid interest when its conditions are met, generally including paying the required balance in full by the due date. Carrying another balance may change that protection. Check your account instead of assuming a tuition charge is automatically interest-free.[3]
| Route | Costs to check | Timing to confirm |
|---|---|---|
| Bank payment | Any school or bank charge | Funds available before the school deadline |
| School installment plan | Enrollment or installment fees; late-payment terms | Installment dates and registration consequences |
| Credit card | Processing fee, interest, any annual fee, and usable rewards | Posting date, statement due date, and promotional end date |
On a small screen, swipe across the table to see every column.
If you need months to repay, calculate financing costs separately. A promotional purchase APR does not erase a processing fee, and a minimum payment does not show that the balance will be cleared before the promotion expires. Compare the school’s payment plan on the same repayment schedule.
A final check before submitting the payment
- Save the checkout total, fee disclosure, and refund policy.
- Confirm the amount fits your available credit, including the fee.
- Verify any bonus terms and leave room for posting delays.
- Set aside the cash or write a realistic repayment schedule before charging.
- Save both the school receipt and the card transaction confirmation.
For our $5,000 example, ordinary 2% rewards do not justify a 2.85% fee. The answer changes only when a real, incremental benefit exceeds the fee and any borrowing cost. If you cannot demonstrate that with your own numbers, the lower-cost school payment method is the clearer choice.
Sources and verification
Terms checked October 17, 2026 (Korea time). Offers and account terms can change. Examples labeled hypothetical are calculations, not product offers.