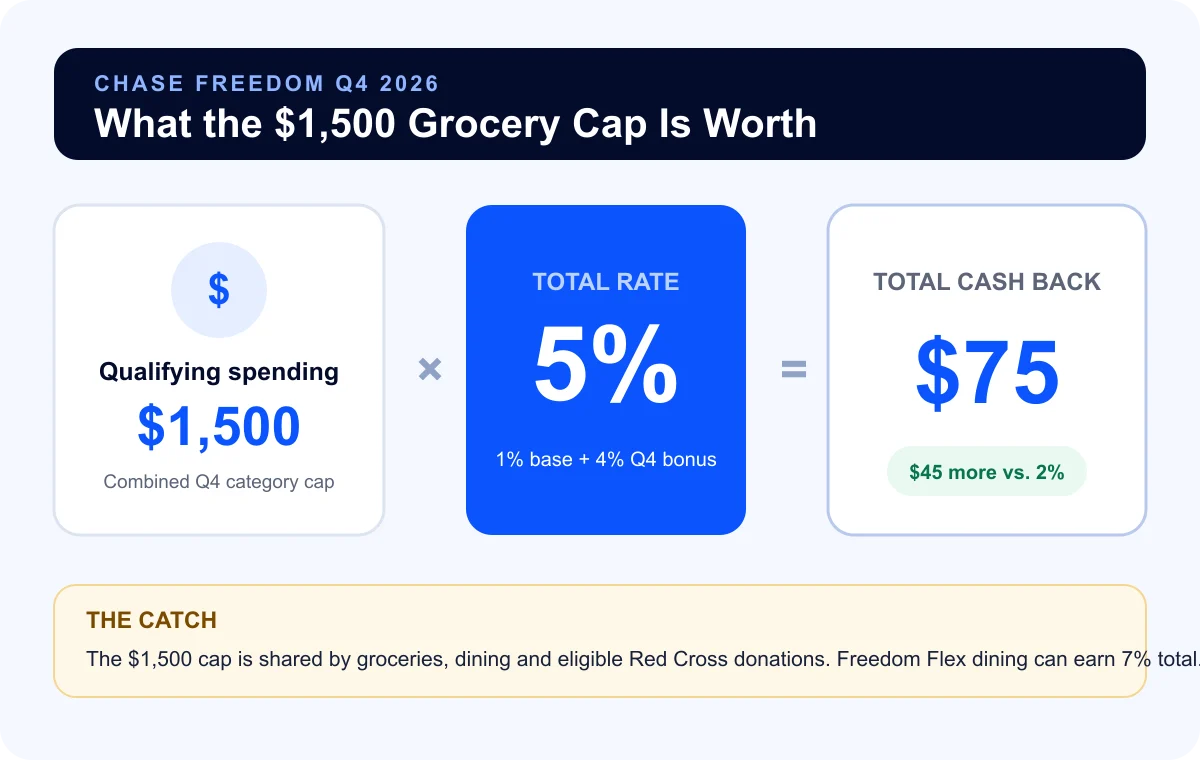
The Chase Freedom Flex Q4 2026 bonus raises a practical question: should groceries or dining get the cap? A $75 grocery reward sounds straightforward. The more useful question is how much better it is than the card you would otherwise use. On $1,500 of spending, a 5% return beats a 2% return by $45—not $75.
Before allocating the quarter’s spending, check what counts as grocery-store spending. For purchases after the bonus limit, see what happens when you hit a cash-back cap.
That difference is the starting point for planning the quarter. You do not need to buy more food, rearrange every shopping trip, or chase a perfect rewards total. You need enough eligible spending at the right price, plus a plan for purchases after the cap.
Valid for October 1–December 31, 2026. Activate by December 14, 2026.
For the other dates to track this quarter, see the Q4 2026 credit card deadline calendar.
What to Know Now
Chase’s Q4 announcement lists groceries, dining and eligible American Red Cross donations. These categories share a $1,500 spending cap within each eligible account. Grocery purchases earn 5% within the activated allowance; Walmart and Target are excluded. Make qualifying donations through Chase’s designated American Red Cross channel.
Have both Freedom and Freedom Flex? Each separate account has its own $1,500 allowance and needs separate activation, according to Chase’s FAQ. Two eligible accounts therefore provide $3,000 of combined capacity, not a single shared $1,500 pool. Additional cards on the same account do not create a second account allowance.
Freedom Flex dining: 1% base + 2% regular dining bonus + 4% quarterly bonus = 7% within the activated cap. Afterward, ordinary eligible dining earns 3%; groceries generally earn 1%. Freedom Flex has a $0 annual fee. See the product terms for other reward categories.
Original Freedom: Its standard Q4 dining return is 5% within the activated cap, then 1%, rather than Flex’s 7% and 3%. The allocation calculations below apply to Freedom Flex only, excluding any account-specific promotional offers. See the original Freedom FAQ.
Chase Freedom Flex Q4 2026: Grocery Math
| Eligible spending | At 5% | At 2% | Extra value |
|---|---|---|---|
| $300 | $15 | $6 | $9 |
| $900 | $45 | $18 | $27 |
| $1,500 | $75 | $30 | $45 |
These are calculations, not additional issuer benefits. They assume every purchase qualifies and no earlier spending has used the allowance. A household with only $900 of eligible spending can still get value; leaving the remaining allowance unused is not a loss that needs to be fixed through extra purchases.
Price matters more than the rewards label. Suppose your normal basket costs $100 and earns 2%, leaving a $98 cost after rewards. At a qualifying store charging $104, a 5% reward leaves a $98.80 cost. The higher reward rate does not compensate for the higher shelf price.
Should Groceries or Dining Get the Cap?
Start with the reward you would give up elsewhere. A higher total rate does not automatically make a category the better use of limited bonus capacity.
Consider $1,500 of eligible grocery purchases and $1,500 of eligible dining. Assume an existing 2% fallback for groceries and Freedom Flex’s regular 3% dining rate outside the promotional allowance.
| Allocation | Groceries | Dining | Total |
|---|---|---|---|
| Groceries use the allowance | $75 | $45 | $120 |
| Dining uses the allowance | $30 | $105 | $135 |
Dining-first wins by $15 in this example. But change the alternative cards and the answer can reverse. If dining could earn 5% elsewhere while groceries would earn only 1%, grocery-first produces $150 versus $120 for dining-first. Neither comparison is a recommendation to open another account; the alternative rates are assumptions for cards you might already hold.
The practical calculation is: promotional rate minus the best realistic alternative rate. Apply that difference to purchases you can actually redirect before the allowance is consumed.
To reserve capacity for dining, use another card for groceries from the start of the quarter. You cannot earmark the allowance afterward: earlier eligible purchases consume it as they are processed. If you later change the plan, work with the capacity still available.
Two Household Examples
1. $400 a month at qualifying supermarkets
Across three months, $1,200 earns $60 at 5%, compared with $24 at 2%. The incremental value is $36. That is a useful result without reaching the maximum. Other eligible categories may use the remaining capacity, but spending more is not necessary.
2. A $600 food budget, but only half is eligible
Assume $300 a month qualifies and the other $300 does not. The eligible quarterly total is $900, producing $45 at 5%. If the other $900 goes on an accepted 2% fallback, total rewards are $63. Putting the whole $1,800 on a 2% card would produce $36. The category strategy adds $27—not 5% of the entire food budget.
After the bonus is exhausted, compare the ordinary rate on your next purchase with your other cards.
Before Your First Purchase
- Activate and retain confirmation. Do this before shopping rather than relying on a last-minute deadline.
- Check the merchant. Chase’s grocery definition excludes warehouse clubs and other nonqualifying store types; delivery depends on how the merchant classifies the transaction. Read the category rules.
- Track the combined allowance. Keep one running total for all eligible quarterly categories.
- Choose the overflow card. Make that decision before the next checkout.
- Leave processing time. Chase’s FAQ requires the purchase to post by December 31; an order charged at shipment may miss the quarter.
To check capacity, sign in, select the relevant card and open its rewards area. Review quarterly-category progress if displayed, then reconcile it with posted rewards activity and statements. Subtract eligible spending from $1,500 for that account; do not use your full statement balance as the category total. If the tracker is unclear, ask Chase to confirm remaining capacity.
Get card deadline alerts
A short email before key card deadlines, like Chase’s December 14 Q4 activation cutoff.
The Bottom Line
For Chase Freedom Flex Q4 2026, the best plan starts with your normal spending, not the maximum possible reward. Use the category bonus where it adds the most value, keep prices in the comparison, and change cards when the bonus no longer applies.
For a year-round food-budget comparison, see CardTuned’s groceries-and-dining guide.
Update Log
- 2026-09-24 — Verified account-level caps and card-specific dining rates; clarified allocation and quarter-end guidance.
Methodology and Sources
Chase records cash-back rewards as points; these examples use cash redemption at 1 cent per point. Examples are original calculations using the stated rates and hypothetical budgets. They assume eligible purchases, successful activation, available bonus capacity and no interest, fees, returns, welcome bonuses or special redemption values. Alternative 1%, 2% and 5% rates are comparison assumptions, not promises about an unnamed card. This is educational information, not individualized financial advice.
Explore these cards
Review fees, rewards and conditions, and add cards to your comparison.